One Annuity Fee That Compounds Against a Benefit Base That Never Pays Out
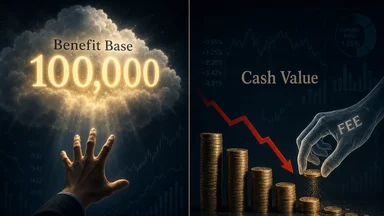
You buy an annuity for guarantees. The contract promises a future income stream, and a rider—often a guaranteed lifetime withdrawal benefit (GLWB)—adds a layer of security. But that rider comes with a fee, typically 0.5% to 1.5% of something called the benefit base. Problem is, the benefit base is a phantom number. It is an accounting entry used to calculate future withdrawals, not a balance you can cash out. Meanwhile, the fee compounds each year against that phantom base, eating into the real cash value that actually supports the contract. This article explains how that fee works, why it persists, and what it costs you.
The Annuity Fee That Grows a Phantom Number
The benefit base is the notional amount on which the insurer calculates your guaranteed lifetime withdrawals. It often starts equal to your premium, then grows each year by a fixed percentage (say 5% or 6%) or by market gains, whichever is higher. But you cannot withdraw that base as a lump sum. It is a paper number—a multiplier used to determine how much you can take out each year for life, typically 4% to 6% of the base.
The rider fee is deducted annually from the cash value of the annuity, not from the benefit base. The cash value is the actual account that fluctuates with market performance and fees. The fee is typically 0.5% to 1.5% of the benefit base, even if the cash value is lower. So if your benefit base is $100,000 and the fee is 1%, the insurer takes $1,000 from the cash value each year—regardless of whether the cash value is $100,000 or $80,000. Over time, this fee compounds. In a flat market, after 20 years, that 1% fee on a $100,000 base would consume roughly $22,000 from the cash value, assuming the base stays constant. But the base often grows, so the fee can increase each year. The cash value erodes faster than the base grows, creating a widening gap between the phantom number and the real money.
The insurer collects this fee every year, no matter how the market performs. In down years, the fee becomes a larger percentage of the diminishing cash value. Some contracts allow the fee to be waived if the cash value drops to zero, but by then the policy is essentially worthless. The fee is a guaranteed revenue stream for the insurer, funded by the policyholder's real assets.
Why the Benefit Base Exists and What It Promises
The benefit base exists to make a promise: that you can withdraw a certain amount each year for life, even if your cash value runs out. The GLWB rider guarantees that you can take, say, 5% of the benefit base annually until death. If the cash value hits zero, the insurer continues to pay that amount from its own funds. That is the guarantee you pay for.
But the benefit base is not a savings account. It is a calculation tool. It grows by a formula—often a simple roll-up rate or a step-up based on market highs. The insurer sets these terms to manage its risk. The base can climb nicely on paper, but the cash value that funds the guarantee may lag behind, especially after fees.
For example, a $100,000 premium might have a benefit base that grows to $200,000 over 15 years at a 5% roll-up. The guaranteed withdrawal might then be 5% of $200,000, or $10,000 per year. But the cash value might be only $120,000 after fees and market returns. You can withdraw $10,000 annually, but if you surrender the contract, you get only the cash value—$120,000—not the $200,000 base.
Beneficiaries get the cash value, not the benefit base. If you die before annuitizing, your heirs receive whatever is left in the cash value, which may be substantially less than the base. The benefit base vanishes at death unless a specific death benefit rider is purchased separately. The base is a promise for lifetime income, not an inheritance.
How the Fee Compounds Against a Vanishing Payout
The rider fee is deducted from the cash value, which is the actual investment account. Over time, this fee can significantly reduce the cash value, especially if market returns are modest. A study by Voya Financial (cited in a 2019 white paper) illustrated that a 1% rider fee on a GLWB could reduce cash value by over 30% after 20 years compared to a no-rider scenario, assuming moderate returns.
Consider a policy with a $100,000 premium, a 5% roll-up on the benefit base, and a 1% rider fee. In a year where the market returns 0%, the cash value earns nothing, but the fee is still deducted. The benefit base grows by 5% to $105,000, while the cash value drops by $1,000 (the fee) plus any other mortality and expense charges. After a few flat years, the cash value can fall far below the base.
The compounding is insidious. In year one, the fee is $1,000 on a $100,000 cash value—1%. But if the cash value drops to $80,000 after several years, the fee is still $1,000 (based on a base that may have grown to $115,000), which is now 1.25% of cash value. The effective cost rises as the cash value shrinks.
In a severe market downturn, the cash value can decline while the fee continues. The net result is that the benefit base climbs—thanks to the roll-up—while the real account shrinks. The gap widens, and the guarantee becomes less meaningful because the cash value may be exhausted before the lifetime withdrawals kick in. Some policies allow the guarantee to continue even after cash value hits zero, but that depends on the contract terms.
The Insurer's Profit Machine Beneath the Guarantee
Insurers are in the business of managing risk and making a profit. The rider fee is their primary revenue source for the GLWB guarantee. They use a portion of the fees to hedge their risk—buying derivatives or bonds that pay off if markets fall—and the rest is profit. The hedge cost is typically lower than the fee, leaving a margin.
Lapse rates are a key assumption. Many policyholders surrender their annuities before they start taking lifetime withdrawals, often due to a change in financial circumstances or dissatisfaction with returns. When they surrender, they forfeit the benefit base and get only the cash value, which has been reduced by fees. The insurer keeps the accumulated fees and does not have to pay the guarantee. Industry data suggests that only a small fraction of contracts—some estimates put it at 2% to 5%—actually pay out the full benefit base as lifetime income.
Surrender charges lock clients in for a period, typically 5 to 10 years. These charges are separate from the rider fee and can be steep—often 7% to 10% in the early years, declining to zero. If you need to exit early, you lose a chunk of your cash value on top of the rider fees already paid. This lock-in ensures the insurer collects fees for a minimum number of years.
The internal costs are often hidden in the fine print. The rider fee is disclosed, but the total cost includes mortality and expense charges, administrative fees, and underlying fund expenses—all layered on top. A typical variable annuity with a GLWB rider might have total annual expenses of 2.5% to 3.5% of the cash value, with the rider fee being about a third of that. The benefit base fee is just one piece of a larger cost structure.
Comparing Annuity Fees to Equivalent Market Costs
By contrast, a low-cost index fund has an expense ratio of 0.03% to 0.10% annually. No rider fee, no mortality charges. Over 30 years, a 1% annual fee reduces the final portfolio value by roughly 25% compared to a no-fee scenario, assuming 6% gross returns. The rider fee on a GLWB is typically 1% or more, on top of the underlying fund costs, which can add another 0.5% to 1.5%.
The GLWB promises a lifetime withdrawal stream, similar to the 4% rule often cited in retirement planning. But the 4% rule is a withdrawal guideline from a self-managed portfolio, not a guaranteed income. With a GLWB, you pay for the guarantee that the withdrawals continue even if the account goes to zero. The trade-off is that you accept lower upside potential and higher fees.
Morningstar's 2023 report on annuity fees found that the median GLWB rider fee was 1.1% of the benefit base. That is on top of the annuity's other costs. For a $100,000 investment, that is $1,100 annually, every year, regardless of market returns. Over 20 years, even if the base does not grow, that's $22,000 in fees. If the base grows, the fee grows with it.
Some argue that the GLWB provides peace of mind and a hedge against longevity risk—the risk of outliving your savings. That is a valid benefit. But the cost is high, and the fee structure is opaque. A self-managed portfolio with a systematic withdrawal plan can achieve similar outcomes without the fee drag, though it lacks the insurance guarantee. The decision depends on individual risk tolerance and financial situation.
When the Benefit Base Actually Pays — Rarely
The benefit base pays out only if you take lifetime withdrawals. You must annuitize or start the withdrawal phase, typically after a certain age. Once you start, you receive a fixed percentage of the benefit base each year for life. But if you die early, your beneficiaries get the cash value, which may be far less than the base. If you surrender the contract, you get the cash value minus any surrender charges—the base disappears.
Statistical life expectancy means that many policyholders will not live long enough to collect the full value of the guarantee. For example, a 65-year-old male has a life expectancy of about 84 years. If he starts withdrawals at 65, he might collect for 19 years. The benefit base might have grown to $200,000, and he withdraws 5% annually ($10,000). Over 19 years, he collects $190,000—less than the base. Meanwhile, the cash value may have been exhausted, so the insurer pays the remaining years from its own funds. But the total payout is capped by the withdrawal percentage and life span.
Industry data suggests that only a small fraction of GLWB contracts—some sources say 2% to 5%—result in the insurer paying out the full benefit base as guaranteed income. Most policies either lapse, are surrendered, or the policyholder dies before the guarantee is fully utilized. The insurer prices the rider fee assuming a certain lapse rate and mortality experience, and the fee is set to ensure profitability even if only a few contracts pay out fully.
The guarantee is real, but its value is contingent on living long enough and not needing to access the cash value early. For many, the fee is a recurring cost that erodes the very account meant to provide retirement income. The benefit base remains a promise that seldom delivers its full face value.
What to Ask Before Signing Any Annuity Rider
Before you purchase an annuity with a GLWB or similar rider, request a cash-value projection that shows the impact of the rider fee over time. Ask the agent to illustrate a scenario with 0% market returns—what happens to cash value and benefit base after 10, 20, 30 years? The projection should show the fee deduction explicitly.
Compare the rider cost to a simple fixed-indexed annuity without the rider. The difference in fees may be 1% or more annually. Ask whether the guarantee is worth that cost given your health and life expectancy. If you have a shorter life expectancy, the rider is less valuable.
Check the surrender schedule and penalty period. How long are you locked in? What is the penalty if you need to withdraw more than the allowed amount? Some contracts allow penalty-free withdrawals up to 10% per year, but excess withdrawals may trigger a reduction in the benefit base.
Ask bluntly: “If I die in year 5, what does my heir get?” The answer will be the cash value, which after fees and market performance may be less than your premium. The benefit base is irrelevant at death unless a specific death benefit rider is attached.
Run the numbers with a flat 0% return scenario. This is not unrealistic—markets can stagnate. If the cash value is eroded by fees, the guarantee may still pay lifetime withdrawals, but your heirs get nothing. Understand that the fee is a cost you pay every year for a promise that may never fully materialize.
Finally, read the prospectus carefully. Look for the total annual fee, including rider fees, mortality and expense charges, and underlying fund expenses. Compare that to a low-cost alternative like an index fund paired with a simple fixed annuity for guaranteed income. The difference in fees can be hundreds of thousands of dollars over a retirement horizon.
This article is for informational purposes only and does not constitute personalized financial or investment advice. You should consider consulting a qualified professional before making any decisions about annuity products.